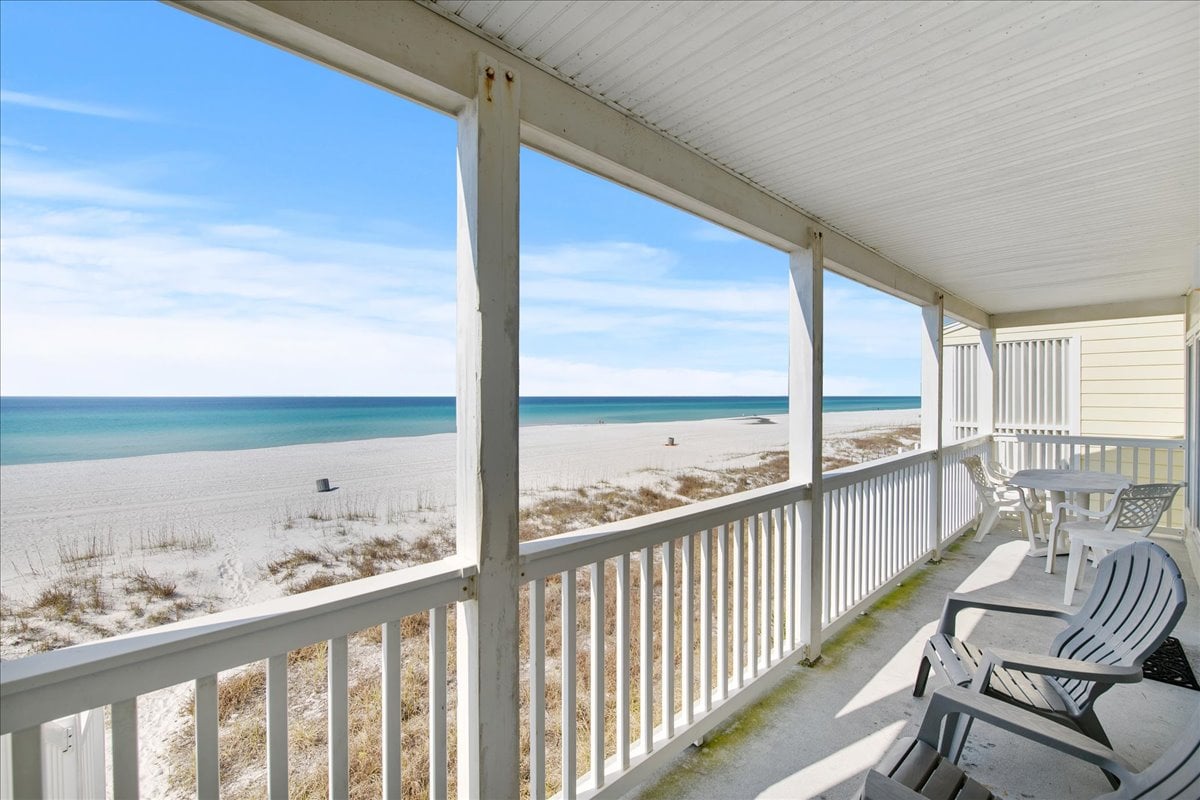
Before You Buy a Jersey Shore Condo, Understand What the Association Really Covers
October 26, 2026
October 26, 2026
There's something appealing about owning a condominium at the Jersey Shore.
For many buyers, it's the opportunity to enjoy a beach getaway without taking on all the responsibilities that come with maintaining a traditional single-family home. You can spend your weekends enjoying the beach, restaurants, and everything that makes our shore communities special, hopefully without worrying about mowing the lawn or maintaining an entire property on your own.
But one of the most common misconceptions about condominium ownership is that the association takes care of everything outside your front door.
Unfortunately, it's not always that simple.
Whether you're considering a condominium in Ocean City, Margate, Ventnor, or another South Jersey shore community, understanding what you're actually purchasing is an important part of making a smart real estate decision.
And in some cases, the details buried in the condominium documents can be just as important as the features you notice during a showing.
When buyers hear the word "condominium," they often picture a large building with multiple units, shared hallways, elevators, and professional management.
Those properties certainly exist along the Jersey Shore, but they're only one type of condominium ownership.
In Ocean City, for example, many properties that look like traditional two-family beach houses are legally structured as condominiums.
You might purchase the first-floor unit of a duplex, with another owner occupying the second floor. Each owner has a separate living space, but the property may share certain structural components, exterior features, and common areas.
These smaller associations can operate very differently from larger condominium buildings.
Some have professional management companies, established reserve accounts, and detailed maintenance procedures.
Others may consist of only two or three owners who coordinate expenses and decisions among themselves.
Neither arrangement is necessarily better.
However, the financial responsibilities, decision-making process, and level of involvement required from individual owners can be substantially different.
That's why I encourage buyers to look beyond the property description and understand the actual ownership structure.
One of the first questions buyers should ask is what expenses are included in the association fees.
Depending on the property, condominium fees may contribute toward items such as exterior maintenance, common-area insurance, landscaping, trash removal, shared utilities, building management, and reserves for future repairs.
In larger buildings, fees may also support elevators, pools, fitness facilities, parking areas, and other shared amenities.
But these services are not universal.
A smaller Ocean City condominium association might have relatively modest fees because owners handle certain responsibilities directly.
Another association may charge substantially more because it provides additional services or maintains expensive shared amenities.
It's important not to assume that a higher monthly fee is automatically a disadvantage.
A well-funded association that regularly maintains its property may be financially healthier than one with unusually low fees and little money set aside for future expenses.
The more useful question is whether the fees are appropriate for the property's needs and whether the association has a realistic plan for ongoing maintenance.
This is one of the most important questions I encourage shore condominium buyers to investigate.
Imagine purchasing a beautiful second-floor unit in a duplex. The interior has been updated, the location is excellent, and the property seems to be in wonderful condition.
A year later, the building needs a new roof.
Who pays?
You might assume the expense is divided equally between the two owners, but the actual answer depends on the condominium's governing documents.
Some associations allocate certain expenses equally. Others use ownership percentages or have provisions assigning responsibility for specific components.
The same questions can arise with siding, decks, stairways, foundations, exterior painting, and other shared elements.
In coastal communities, where buildings are exposed to salt air, wind, moisture, and severe weather, these responsibilities deserve careful consideration.
Before purchasing, buyers should review the master deed, bylaws, and other applicable association documents to understand which components are considered common elements, limited common elements, or individual unit responsibilities.
These distinctions may sound technical, but they can have very real financial consequences.
It's easy to be attracted to a property with minimal condominium fees.
After all, lower monthly expenses can make a second home feel more affordable.
But there's an important difference between an association that has low operating expenses and one that simply isn't setting aside enough money for future repairs.
Consider a small condominium association that collects only enough to pay its annual insurance and routine expenses.
If the building later requires a major roof replacement, exterior renovation, or structural repair, the owners may need to contribute additional funds.
This is commonly referred to as a special assessment.
Depending on the nature of the work and the number of units involved, those expenses can be substantial.
A buyer who focused exclusively on the low monthly fee may be surprised to discover that a significant repair expense is coming due.
That's why it's important to ask whether the association maintains reserve funds, how those reserves are managed, and whether major projects are anticipated.
For larger associations, reviewing financial statements, budgets, reserve studies, and meeting minutes can provide valuable insight.
For smaller associations, the available records may be less extensive, making direct questions and careful document review even more important.
A low monthly fee isn't necessarily a bargain if it comes with significant financial uncertainty.
Special assessments are additional charges imposed by a condominium association to cover expenses that aren't adequately funded through regular association fees or existing reserves.
They may be used for major repairs, improvements, insurance-related expenses, or other association obligations.
At the Jersey Shore, projects involving roofs, siding, decks, structural components, and exterior maintenance can be particularly important because of the coastal environment.
Before purchasing a condominium, buyers should ask whether any special assessments have been approved, are currently being collected, or are under consideration.
It's also worth reviewing association meeting minutes, when available, to identify discussions about upcoming projects.
If an assessment has already been approved, the purchase contract should clearly address how that expense will be handled between buyer and seller.
And even when no assessment is currently planned, buyers should consider the association's financial position and the age and condition of the building.
No one can predict every future expense, but understanding the property's maintenance history and financial reserves can help reduce unpleasant surprises.
Insurance is another area where condominium buyers sometimes misunderstand their responsibilities.
Most condominium associations maintain some form of master insurance policy covering specified portions of the building or common property.
However, the scope of that coverage varies.
Some policies may cover certain building components while leaving individual owners responsible for interior finishes, personal property, improvements, liability, and other exposures.
Owners may need their own condominium insurance policy, commonly referred to as an HO-6 policy, to address applicable risks.
At the Jersey Shore, flood insurance is an additional consideration.
A condominium association's flood coverage, if any, may not protect everything an individual owner assumes it does.
Coverage limits, deductibles, exclusions, and the distinction between association and individual responsibilities all matter.
Buyers should review the association's insurance information and speak with a knowledgeable insurance professional before purchasing.
It's also important to understand whether the association has large deductibles that could result in additional costs being allocated to unit owners after a claim.
The objective is to avoid discovering a gap in coverage after a loss has already occurred.
For many Jersey Shore buyers, rental potential is an important part of the purchasing decision.
Some buyers plan to enjoy the property personally while renting it for several peak summer weeks to offset expenses.
Others are primarily interested in rental income.
But not every condominium permits the same rental arrangements.
Association governing documents may restrict rental duration, limit the number of rentals permitted, require minimum lease terms, or establish other rules.
Municipal rental regulations may impose additional requirements.
For example, a buyer considering an Ocean City condominium should investigate both the property's association restrictions and the applicable local rental requirements.
A property that appears ideal for weekly summer rentals may not allow the rental arrangement the buyer has in mind.
Similarly, a building that permits seasonal rentals today may have governing documents that establish procedures for changing certain rules in the future.
Rental income projections should always be evaluated in light of these restrictions.
Before relying on potential rental income to support a purchase, buyers should confirm what is actually permitted.
At the shore, parking can be one of the most valuable features of a property.
The same is true of private decks, storage areas, outdoor showers, and designated spaces for beach equipment.
But buyers shouldn't assume that a feature belongs exclusively to a particular unit simply because it's currently being used that way.
In a condominium, certain areas may be individually owned, assigned for exclusive use, or classified as common elements shared by multiple owners.
Those distinctions can affect how the space may be used, maintained, altered, or transferred.
For example, a deck may be reserved for the use of one unit while certain maintenance responsibilities remain with the association or are allocated according to the governing documents.
Parking spaces may be deeded, assigned, or governed by association rules.
Storage areas may also be subject to restrictions.
Before purchasing, buyers should verify that the legal documents accurately reflect the parking, storage, and outdoor features being represented.
This is particularly important in smaller shore condominiums where informal arrangements between existing owners may have developed over time.
An understanding between current owners doesn't necessarily establish a permanent legal right for future owners.
In a large condominium association, decisions are typically made through an established board and voting procedures.
In a two-unit or three-unit association, the process may be much more personal.
Imagine two owners sharing responsibility for a building.
One believes the exterior needs immediate painting, while the other wants to postpone the expense.
Or one owner wants to replace a shared component with a higher-end material, while the other prefers a more economical option.
How are those disagreements resolved?
The association's governing documents should establish procedures for decision-making, expense allocation, and dispute resolution.
Buyers should understand how major maintenance decisions are approved and what happens when owners cannot agree.
This doesn't mean small condominium associations are inherently problematic.
Many operate successfully for years with cooperative owners and clear expectations.
But when you're purchasing into a shared ownership arrangement, the quality of the governing documents and the association's operating practices can have a meaningful impact on your experience.
A beautiful kitchen, updated bathrooms, and a great location can make it easy to fall in love with a shore condominium.
But the legal and financial documents deserve just as much attention.
Depending on the property and what is available, buyers should review the master deed, bylaws, association rules, current budget, financial statements, insurance information, and records of approved or proposed assessments.
Meeting minutes and reserve studies, when available, can also provide valuable insight.
For smaller associations, buyers may need to ask additional questions about how expenses are collected, whether funds are maintained in dedicated accounts, and how major repairs are coordinated.
A qualified New Jersey real estate attorney can help interpret the governing documents, while insurance and financial professionals can address questions within their respective areas of expertise.
It's also important to understand the inspection and document-review deadlines established in the purchase agreement.
The goal is to evaluate these issues while you still have the contractual opportunity to address concerns.
Despite these considerations, condominium ownership can be an excellent option for buyers who want to enjoy the Jersey Shore.
For some, it offers a more manageable alternative to a single-family property.
For others, a condominium provides access to a desirable location, beach proximity, or amenities that might otherwise be outside their preferred budget.
And for buyers who spend only part of the year at the shore, shared maintenance arrangements may offer meaningful convenience.
The key is understanding exactly what you're purchasing.
Two condominiums with similar asking prices and comparable interiors can have very different ownership costs, maintenance responsibilities, and association structures.
Those differences may not be obvious during a showing, but they can become extremely important over time.
Buying a condominium involves more than choosing the right location, floor plan, or view.
You're also becoming part of a shared ownership structure, with financial obligations, governing documents, and responsibilities that may affect how you use and maintain the property.
Whether you're purchasing a modest beach getaway, a luxury condominium, or an investment property in Ocean City, Margate, Ventnor, or another South Jersey shore community, taking the time to understand those details can help you avoid costly surprises.
A great shore property should offer more than an enjoyable summer experience. It should also make sense for your lifestyle, expectations, and long-term financial goals.
If you're considering purchasing a condominium at the Jersey Shore, I'd be happy to help you evaluate your options, understand the questions worth asking, and navigate the process with confidence.
Confident decisions start with clear information.
Amy Reuter | Broker Associate, Berkshire Hathaway HomeServices Fox & Roach, REALTORS®
Reach out by call, text, or DM for more information!
Stay up to date on the latest real estate trends.
There isn't one real estate strategy that's right for every retiring athlete, but there are several questions worth considering before deciding what comes next.

There may be school schedules to consider, cars to transport, temporary housing to arrange and an entire household that can't simply pack up overnight.
Amy Reuter brings together luxury-level marketing, strong negotiation, and honest guidance to help clients navigate every move with confidence. From South Jersey primary residences to South Jersey beach homes, Amy creates a thoughtful, highly personalized experience centered around strategy, communication, and results.
AMY REUTER
[email protected]
(856) 229-2473
ADDRESS
198 FRIES MILL RD
TURNERSVILLE, NJ 08012